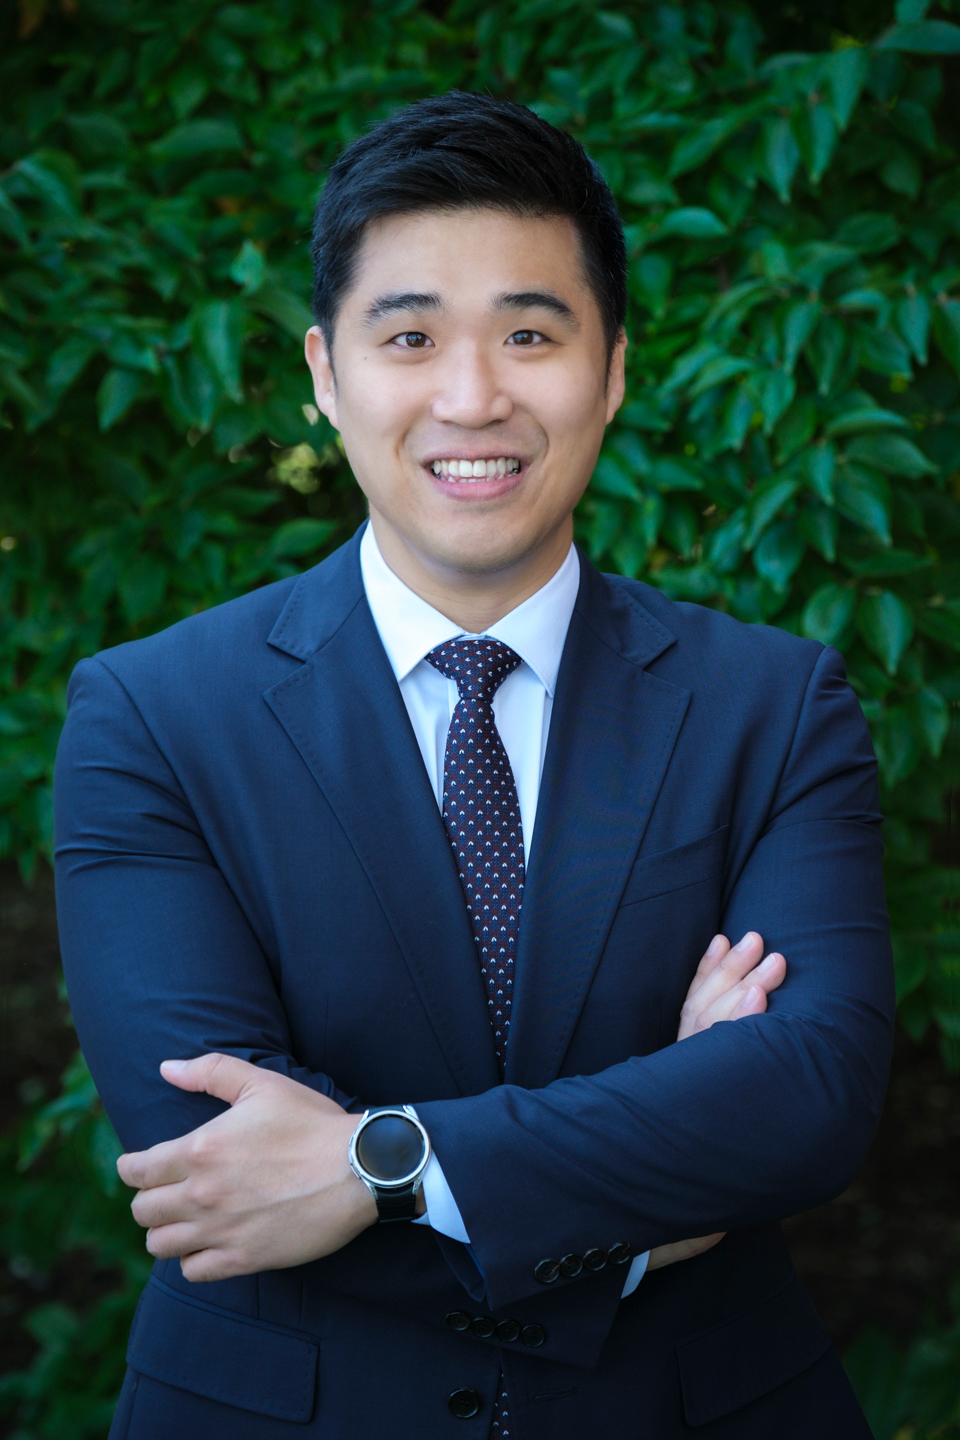
Hi, I’m Nicholas Jaehyun Yi.
I am a Research Fellow at the Seongnam Research Institute. My research interests include macro-finance, banking, and supply-chain dynamics.
Research
Working Paper
“Financial and Production Integration in the Macroeconomy” (with Emanuele Brancati, Qingqing Cao, and Raoul Minetti)
Abstract: This paper studies how integration between the financial sector and supply chains shapes business cycle transmission. We develop a dynamic model in which banks provide asset-based finance to firms in supply chains. The model highlights two integration margins. Extensive-margin integration—captured by firms’ access to banks specialized in different supply chain segments—amplifies banking shocks. By contrast, intensive-margin integration—captured by the diffusion of trade credit factoring and invoice discounting—attenuates banking disruptions. The analysis reveals that the stabilizing effects of integration dominate when firm production linkages are tight. The predictions are consistent with matched bank–firm data from Italy.
Work in Progress
“Securitization, Supply Chain Contagion, and Macroprudential Policy: A Three-Sector DSGE Analysis”
Abstract: This paper develops a three-sector supply chain DSGE model in which sector-specific banks finance trade-credit-linked firms and securitize the receivables they factor, selling them to households through an endogenous, downward-sloping demand curve. Around a shock to midstream bank net worth, three results emerge. First, in normal times deeper securitization markets monotonically dampen the shock, cutting the peak output decline by up to 35 percent relative to a securitization ban. Second, a simultaneous freeze of the securitization market—calibrated to the 2007–09 collapse in U.S. issuance—reverses this benefit: the combined crisis is nearly twice as severe as under prohibition, as banks that can no longer securitize retain risk on already-impaired balance sheets. Securitization is thus a shock absorber in normal times but a shock amplifier in a freeze. Third, a fixed cap on the securitized share—a stylized analog of the Dodd–Frank risk-retention rule—dominates free securitization: it preserves the normal-times benefit and roughly halves the excess crisis loss (the loss beyond the prohibition benchmark)—but does not make securitization safe. A cross-sectional test on bank-level Call Report data corroborates the mechanism.
“Sectoral Bank Credit, Production Chains, and the Choice of an Inflation Target”
Abstract: This paper develops a framework for studying what the location of a credit disturbance within a production chain implies for inflation and for the index a central bank should target. I embed sectoral Calvo pricing, staggered wages, a cost channel of credit and a generalized Taylor rule in a dynamic model of a three-stage production chain in which each stage borrows from its own bank against capital and trade-credit invoices. Firms fund part of their wage bill at their own bank before output is sold, so that a lender’s net worth enters the Phillips curve of one sector and not of another; and the chain passes a cost increase forward to customers but a fall in demand backward to suppliers. Together these make that location a determinant of relative prices rather than of the aggregate alone.
Teaching
Instructor, Michigan State University
- EC302: Intermediate Macroeconomics (Summer 22)
- EC402: Advanced Macroeconomics (Summer 23)
Teaching Assistant, Michigan State University
Undergraduate
- EC202: Introduction to Macroeconomics (Spring 22, Spring 23, Spring 24, Fall 24)
- EC302: Intermediate Macroeconomics (Fall 20, Spring 21, Fall 23, Spring 25)
Graduate
- EC813A: Macroeconomics Ⅰ (Fall 21, Fall 22)